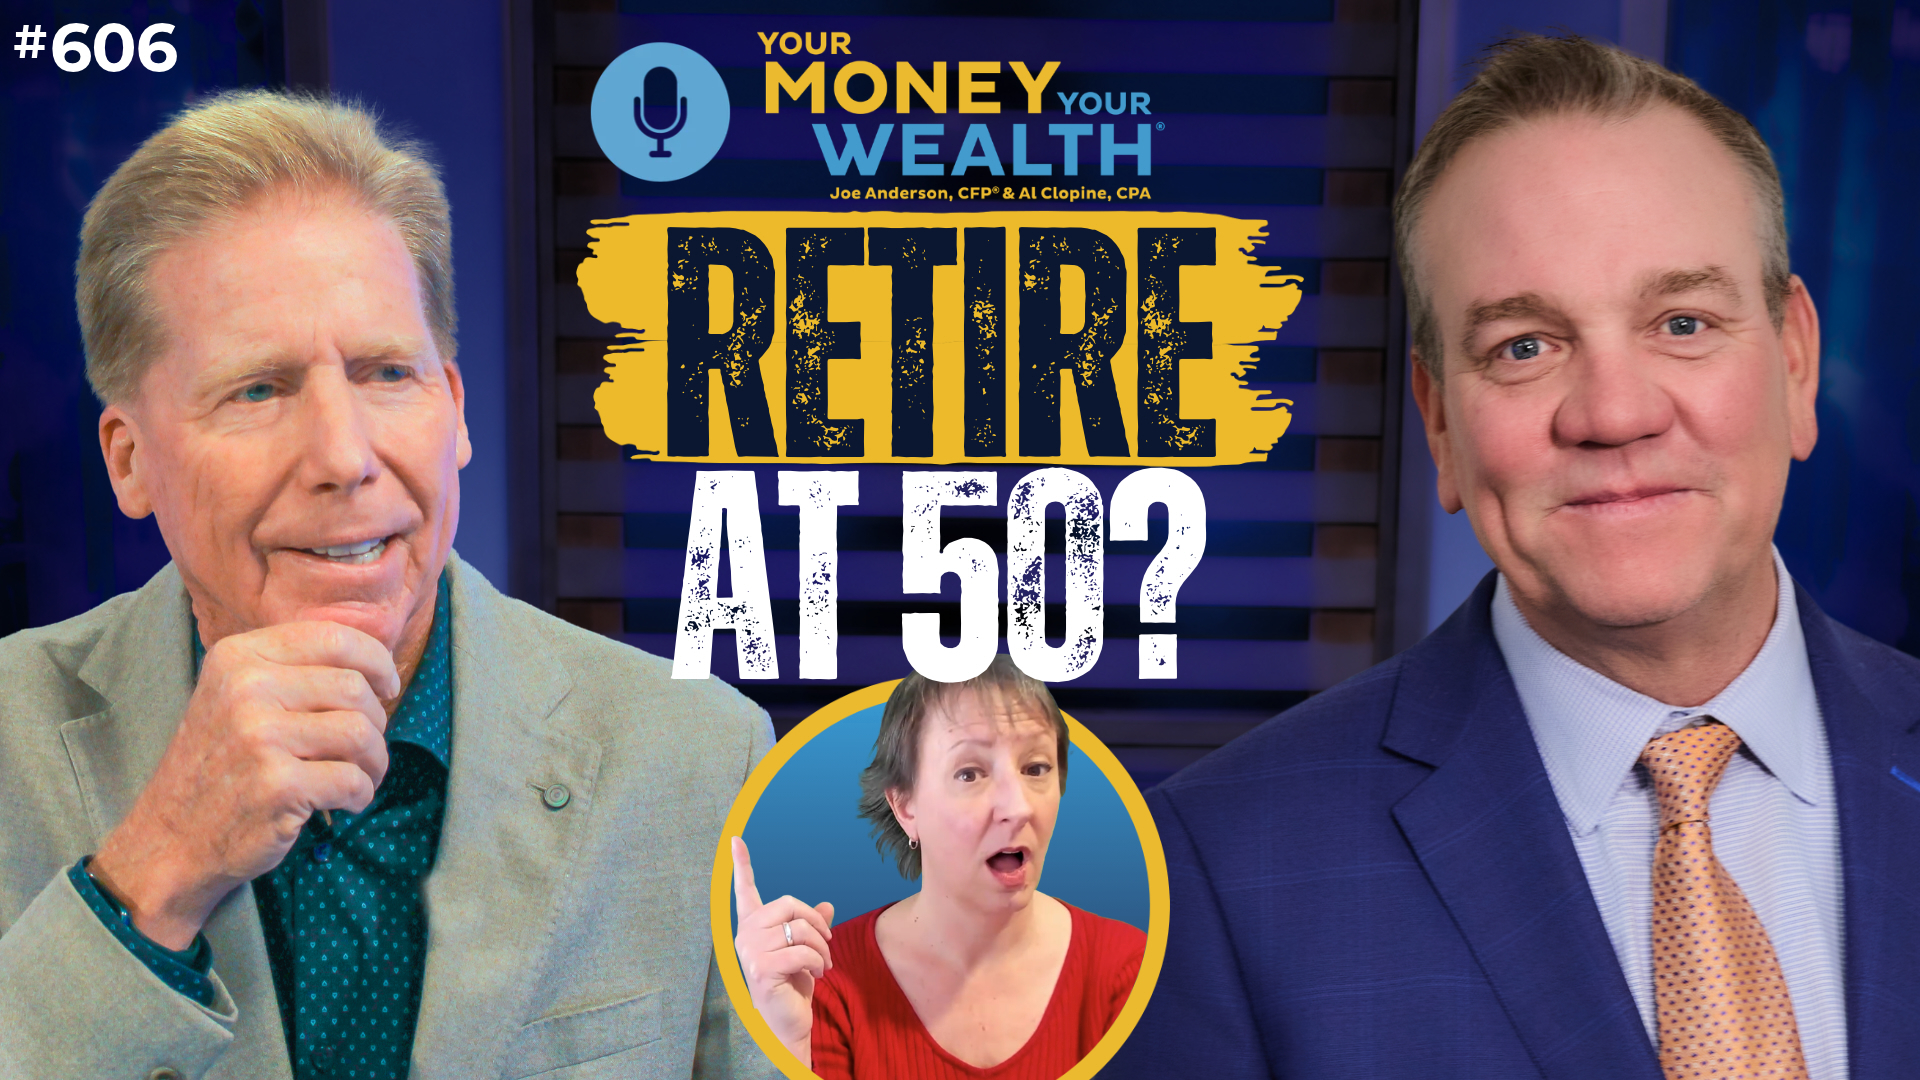
Financial situations around early retirement today on YMYW: Shane and Ilya are 38 and 37. Ilya has a big federal pension and lifetime health insurance waiting for him at age 50, but he needs out of his job now. Can they still retire early? Rip and Beth are 35 and 33, and Beth can sell her business for $1.8 million. Is that enough for her to be done for good, or would she end up back at work anyway? Leeroy and Belle are teachers with just shy of a million dollars saved at age 34 and 33. Is it crazy for them to take a gap year? Finally, Jake is in his early 50s with $1.1 million, planning to Coast FIRE his way out at age 58. Does the math hold up?
What is Coast FIRE?
Coast FIRE is the point where your invested savings will compound to your full retirement target by traditional retirement age without adding another dollar. From there you work only enough to cover current living expenses. Whether it works for you depends on your actual rate of return, since a lower return than you assumed changes the math.
Frequently Asked Questions
What is a distribution rate?
Your distribution rate is the percentage of your portfolio you pull out each year. Divide your annual withdrawals by your portfolio balance. On this episode Joe and Big Al treated 3.5% as comfortable and called 4% at age 50 tight, since an early retirement has to stretch across more years.
What happens to a pension if you quit before you’re eligible for it?
Leaving before your eligibility age generally converts the benefit into a deferred one that starts later and pays less. A 38-year-old federal employee on this episode described a pension worth $76,000 a year starting at 50 that would be much reduced and delayed to 62 if he left now. Rules vary by system.
What is an installment sale when you sell a business?
An installment sale spreads the purchase price across several payments over multiple years instead of one lump sum at closing. It splits the tax across those years, and it carries the risk that the buyer doesn’t make every payment.
Does taking a gap year in your 30s set back your retirement savings?
A gap year stops new contributions for as long as you’re out. The two teachers on this episode planned to build up cash ahead of time so they wouldn’t have to sell investments during the year, which leaves the invested balance compounding. How much it sets you back depends on how long you’re out and whether you touch the portfolio.
Why is employer health insurance worth so much to someone retiring early?
Retiring before 65 means covering your own health coverage until Medicare starts. On this episode Joe counted a federal employee’s subsidized coverage from 50 to 65 alongside the pension when he sized up what the listener would be walking away from. That valuation was a rough on-air estimate.
Show Notes
- 00:00 – Intro: This Week on the YMYW Podcast
- 00:58 – Quitting Kills My $76K Pension and Health Insurance. Can We Stop Working at 50 Anyway? (Shane & Ilya)
- 12:23 – Should I Sell My Business for $1.8M and Quit at Age 33? (Rip & Beth, KY)
- 24:24 – Two Teachers, $1M Saved, and a Gap Year at 34. Is That Crazy? (Leeroy & Belle, IA)
- 34:21 – Coast FIRE at 52: Can I Stop Saving Now and Retire at 58? (Jake, MI)
- 42:37 – Outro: Next Week on the YMYW Podcast
- 43:37 – The Derails: Giant Ice Cube, Dutton Ranch, Wisconsin’s Brandy Old-Fashioned
Free Financial Resources:
LIMITED-TIME SPECIAL OFFER | DIY Retirement Guide: download by Friday, November 6, 2026!
WATCH Un-Retirement: Why Retirees Are Going Back to Work (And How to Avoid It) – YMYW TV
Guides | Blogs | Educational Videos | YMYW Newsletter | Subscribe on YouTube
Watch today’s podcast episode on YouTube:
Transcription
(NOTE: Transcriptions are an approximation and may not be entirely correct)
Intro: This Week on the YMYW Podcast
Andi: Shane and Ilya are 38 and 37. Ilya has a big federal pension and lifetime health insurance waiting for him at age 50, but he needs out of his job now. Rip and Beth are 35 and 33, and Beth can sell her business for $1.8 million. Is that enough for her to be done for good, or would she end up back at work anyway? Leeroy and Belle are teachers with just shy of a million dollars saved at age 34 and 33. Is it crazy for them to take a gap year? Finally, Jake is in his early 50s with $1.1 million, planning to Coast FIRE his way out at age 58. Does the math hold up? We’ll find out today on Your Money, Your Wealth® podcast number 606. Tell your friends we’re making fun of finance over here on YMYW, leave your honest ratings and reviews for us in Apple Podcasts and any other app that accept them, and help us reach more people like you. I’m Executive Producer Andi Last, and here are the hosts of Your Money, Your Wealth®, Joe Anderson, CFP® and Big Al Clopine, CPA.
Quitting Kills My $76K Pension and Health Insurance. Can We Stop Working at 50 Anyway? (Shane & Ilya)
Joe: Let’s go to- Shane and Lyle, or Alla? What, what- help me out, Andi
Andi: Shane and Ilya. It’s from a TV-
Joe: Ilya?
Andi: it’s from a, romance novel, I guess, that actually got turned into a show called, Heated Rivalry.
Al: Oh.
Joe: L-L-Y-A.
Andi: I-L-Y-A.
Al: I- I-I-L-Y-A … Ilya. It, well, it looks… see, that’s the, weird thing about, you know, capital I is it looks the same as an L.
Joe: Right.
Andi: But It’s, it’s Ilya. It’s Shane Hollander and Ilya Rozanov, the central characters of Heated Rivalry, a bestselling sports romance novel by Rachel Reeve, and its Crave television adaptation. So this is Shane and Ilya.
Al: You haven’t read that novel?
Joe: I have not. No. I have not. Never.
Al: Never heard of it. Me neither.
Joe: Okay.
Al: All right.
Joe: Let’s, “My husband Shane and I are 38, 37, and we have a two-year-old. Yes, we are two men.”
Al: Okay, cool.
Joe: All right. “I am a US federal employee, and Shane works for an international charity.” Right. “We lived overseas most of our career. Thanks to early career bonuses and holding back on lifestyle inflation, our assets are Roth IRAs, 300,000, traditional IRAs, 100 grand, brokerage account, a million bucks, Al.”
Al: That’s very good.
Joe: 30… How old are they? 38, 37? 38, 37. Damn.
Al: Yep.
Joe: got a TSP, 401(k) at 400,000. Net worth, less real estate, is close to $2 million, 1.9 million. real estate equity is 350,000. I currently pull about 150,000 gross pay per year- and Shane pulls down 100. Our expenses are about $120,000. I would qualify for a pension at age 50 that I project will pay $76,000 a year until I qualify for Social Security at 62, at which point it reduces to 60,000 until I die, and half of that for Shane is left after I die.
If I retire at 50, I qualify for the same health insurance I have until Medicare with minimum premiums. Okay. I was on track to retire at 50 with those benefits projecting about 4 to 6 million dollars in our portfolio, assuming continued maxed TSP and IRA contributions, and had anticipated increasing spending to 50 for more travel.
For reasons I cannot continue in my current job in good faith.” All right.
Andi: For reasons, comma, I cannot continue.
Joe: For reasons.
Andi: Yes.
Joe: So in other words- So he’s like, “I’m out of here.”
Al: He can’t,
Andi: in good faith, he can’t keep working there. I’m not specifying what the reasons are, but for reasons I cannot continue in this job.
Joe: Well, he’s a US federal employee and gets to retire at 50 with full benefits and a pension. What do you think he does?
Al: US federal. So, We- You think, like, an, some kinda agent?
Joe: I think so.
Al: Yeah.
Joe: I think so.
Al: he doesn’t agree with what they’re doing maybe.
Joe: I don’t know. He’s a spy.
Al: Yeah.
Joe: Yeah, CIA.
Right? I don’t know.
Al: I think this just got more interesting.
Joe: It did.
Al: Yeah.
Joe: And he’s like a s- secret agent man.
Al: Yeah. I don’t know. Well, let’s go with that.
Joe: Ve- very confidential.
Al: Yeah.
Joe: I mean, for reasons he cannot k- you know, we, he’s not giving us reasons- No … because it’s, highly Well-
Al: … highly confidential. When you do that, you know we’re gonna make ’em up.
Joe: It’s gonna be great. All right. So l- I mean, with the amount of savings, right, w- for all that money in a non-qualified account, I bet, like, he goes overseas.
Al: Mm-hmm.
Joe: Gets some comp for free, gets a per diem.
Al: Right.
Joe: And he just banks his paycheck. I don’t know.
I’m- But, like, for full retirement at age 50, that, you, have to have, like, an at-risk job.
Al: Yeah.
Joe: It’s not like he’s a clerk- … punching a computer.
Al: Pr- probably not.
Joe: He’s, I think he’s in the field. There’s so-
Al: there’s something there that, Yeah, and, m-
Joe: he’s got some differences with the department, I think.
Al: Yeah.
Joe: Something’s going. Yeah. Something’s going down here.
Al: Yeah,
Joe: But he just can’t continue in my current job in good faith. If I leave my position, I’m confident I can get another one that more or less matches my salary, but there is no replacing the pension insurance benefits.
Al: Okay.
Joe: Shane, keep his salary.
If I leave, my pension is delayed to 62. It would be much reduced.
Al: Yeah.
Joe: Assuming I can keep making our IRA contributions and make equivalent m- max 401(k) contributions over the next 12 years, can we still stop working at 50? I drive a 2013 Kia Morning go-kart. Okay.
Al: Really?
Andi: I’m guessing it’s probably a pretty small car.
Al: Yeah, like one of those little smart cars that fit maybe two people.
Joe: Well, I’m, I might be changing my mind on our boy’s occupation here.
Al: Maybe he’s try- maybe he’s trying to hide his real-
Joe: He’s trying-
Al: Yes …
Joe: yes.
Al: It’s just I’m not gonna-
Andi: Apparently this is the Kia Morning. It does look a little like a go-kart.
Joe: Yeah. That, okay.
Al: I, yeah, I think he’s, it’s just his cover.
Joe: It, could be. It could be.
Al: Well.
Joe: Shane drives a 2017 Kia Soul.
Al: Yeah.
Joe: My drink of choice is bourbon- Mm-hmm … with one big ice cube. Okay, so let’s go back.
Al: All right.
Joe: So- He wants to retire.
He’s, like, Shane is drinking a little gin, and he- Yeah … enjoying different varieties around the world. All right, so-
Al: Y-
Joe: yeah … something’s going on. Can he grin and bear it? Can he suck it up? He’s 38. Can he make it another 12 years? It sounds like no.
Al: Yeah, he says no, so I ran it without that. A- assuming, he can make the same contri- he said he could do the same salary probably, so with that assumption, go forward 12 years.
Joe: So the pension’s paying him $75,000 a year.
Al: I know. It’s hard to walk away from that.
Joe: $75,000 a year.
Al: Yeah.
Joe: I’m gonna go three. That’s, like, almost $3 million.
Al: I, know. It’s, it must be really-
Joe: Plus the health insurance is prob- that, that’s a, $4 million package.
Al: It’s pretty good, yeah, but it’s that bad.
Joe: Man.
Al: So if you just do a little math here, Joe, you start about 1.9 million, and, so it, this would be a 12 year. it would be s- I, did it 6% to be conservative. Sure. Adding 32,000 a year. I don’t know what the exact number is, but I did that. I end up with 4.3 million, so that’s what he’d have. Wanting to spend about 120 right now.
Joe: 4.3 is what he would have in 12 years with- 4,
Al: 4.3.
Yep
Joe: … the same. Just think, it would be, like, almost 9 million included his package.
Al: I would say that he wants us to do the other.
Joe: He wants to get him out.
Al: All right. So, so then spending 120, 3% inflation rate to make it simple, 12 years, 171,000, 171 divided by 4.3, 4.0.
4, 4% distribution rate.
Joe: At 50.
Al: At 50.
Joe: All right. it’s doable.
Al: It’s, it’s-
Joe: He sh- he said Shane’s gonna continue his salary?
Al: Yeah. So I just did it based, well, I think somewhere he said, “Could we retire?” Maybe I, misunderstood that, but at, any rate, I just looked at it, what if they both stop working at the same, when he turns 50?
I would say it’s very close. I think, you know, it’s kind of right on the border, but they could probably do it. May- you know, maybe they gotta- Maybe he has to work a little bit longer. See, that’s the thing. Y- you and I know everyone in their 30s wants to retire at 50, as did I-
Joe: Right …
Al: at, in my 30s. And here I am.
Yeah. Right? So you never know, right? No, but-
Andi: It seems like in Ilya’s case that he’s probably dealing with, like, a, ideological issue with his job-
Joe: Yeah. I-
Andi: … that might all be part of the reason for this …
Al: yeah, I would agree with that. It’s something he-
Joe: Has to
Al: be … something he disagrees with, and, and-
Joe: There’s just a sentence, “For reasons,” comma.
Al: Yeah. Well, and to, to walk away from that much benefit, it’s gotta be fairly important, I would say. Yeah.
Joe: He’s a federal-
Al: Yeah, federal agent. Yeah. So anyway, I think it-
Joe: He didn’t really care for his last mission.
Al: He didn’t agree with it.
Joe: He didn’t agree with it.
Al: No, it’s the wrong mis-
Joe: And Shane was like, “If you, leave and do this mission-
Al: … it’s over.” It’s, over. ”
Joe: I’m gonna take your Kia Morning-
Al: Yeah, Right …
Joe: and drive out of here.”
Al: Oh, man. I, yeah, so but you know what? In this case, so I’m, I’m gonna say it this way, Joe. It’s, close, right?
Joe: Yeah.
Al: it’s probably-
Joe: I mean, happiness is way more important than a couple million bucks.
Al: Yeah. And I would say if he finds a better job and he works to 55, it’s even better.
Joe: Right.
Al: Right? So that’s, which is always gonna be the case. If you work a little bit longer, this looks better.
Joe: Right.
Al: Yeah, 4% distribution rate at 50 is, it might be a little bit tight.
but what you can do, you can figure out ways to reduce your spending if you really don’t wanna work anymore, and I would-
Joe: Okay. They got a two-year-old, and then what? In 12 years, they turn 50.
Al: Mm-hmm.
Joe: Okay?
Al: And s- and so the two-year-old is 14.
Joe: 14, 15. They, the… He’s thinking, “Oh, my two-year-old just want, you know, I wanna spend all this time.”
Al: Yeah, and then they’re 14.
Joe: Guess what? Yeah. No. You’ll have no time. No. You gotta go to work. You’re gonna be bored.
Al: There, yeah, he’s gonna work at least four more years till college
Yeah. It w-
Joe: yeah
Al: just my, my estimate.
Joe: but, I mean, l- at 38 and 37-
Al: Yeah …
Joe: with the net worth that they have- It- … they’ve done a phenomenal job.
It’s, incredible They’ll, be able to retire on ticket at age 50.
Al: Yeah, and they, you know, it may be, it, then, of course, this is based upon a 6% rate of return.
Joe: It, could- It could be,
Al: it could be eight.
Joe: We- It could be 12.
Al: And it could be four. We, you know, we don’t know.
Joe: No, I think if they ke- if he, if they keep saving how they’re saving, with the amount of assets that they’ve accumulated, you know, leave his job, get another one with a similar pay, he could get- Yeah
a job that pays a lot more, too.
Al: It could be, and maybe it’ll have benefits that he’s not even anticipating.
Joe: Exactly. So- Yeah. No, I think do what, your heart tells you to do.
Al: I agree.
Joe: I think they’ve been very disciplined in their savings. Yeah. And, at o- once you get closer to 50, you’ll be like, “All right, hey, you know, maybe I don’t wanna punch.”
Al: yeah. Well, and of course the thing is, a- as you get closer, you run the numbers again, right? and does this r- really work or not? Yep. I mean, 12 years with these assumptions, that, this is a straight line assumption- Yeah … which is not gonna happen. Yeah. So, so we, so the answer’s we don’t know, but if you run a straight line it, you know, it’s pretty close.
Joe: You’re doing well.
Al: Yeah.
Andi: Of the people who go back to work after they retire, about half are not doing it because they miss their coworkers. They need the cash. Un-Retirement: Mistakes That Force Retirees Back to Work is this week’s brand-new episode of YMYW TV. Joe and Big Al walk through the four mistakes that send people back to the grind, and the fix for each one. And this week’s special offer is the DIY Retirement Guide, but it’s only available until this Friday. It is our most popular guide ever and we normally only offer it a few times a year, but a few weeks ago the demand was so high, we realized we better bring it back sooner this time. So if you missed it then, grab it now before the special offer changes sometime this Friday, November 6, for 40+ pages of retirement knowledge you can normally only get in classes or one-on-one meetings with Joe and Big Al’s team at Pure Financial Advisors. Click or tap the links in the episode description to watch Un-Retirement: Mistakes That Force Retirees Back to Work and to download the DIY Retirement Guide before this Friday.
Should I Sell My Business for $1.8M and Quit at Age 33? (Rip & Beth, KY)
Joe: All right. Yeah. Let’s go to Rip and Beth.
Al: Ooh, okay.
Joe: Yeah. Let’s go. “Joe, Big Al, Andi, I have recently added your show to my podcast rotation and find myself listening further and further back.”
Don’t do it. Just don’t. Just, you know what I mean? That’s what these guys all do.
Al: Yeah, right.
Joe: Like, they hear us once and they’re like, “Wow, let’s keep listening,” and then they listen back and it’s like, wow, this is just the same show over and over again.
Al: And they keep thinking-
Joe: And then they stop.
Then they stop listening.
Al: Or they keep thinking it’s gonna get better.
Joe: It’s gonna get better. and it doesn’t
Al: … well, they’re thinking backwards.
Andi: Until they have a question of
their own.
Joe: It only gets worse.
Al: Gets worse. I mean, we’re not, we were not better-
Joe: Yeah
Al: … way back when.
Joe: This is the best right now.
Al: And if you don’t like this…
Joe: Maybe next week it might get a little bit better, but you go backwards, it’s bad. A d- a lot of people do that.
Al: We’ve been, doing this 20 years now.
Joe: 20.
Al: Yeah.
Joe: Yeah.
Al: Yeah.
Joe: Let’s, All right. Well, we got Rip and Beth. Yep. They keep going back. All right, let’s see. Where are we?
Al: Yeah.
Joe: Well, we’re in the rotation for now.
Al: Yeah, at least we’re in the rotation.
Joe: Yes.
Al: That’s all we can aspire to. Yes. We’re one of many. One of.
Joe: Yeah.
Al: Yeah.
Joe: All right. “I find myself listening further back and back. You all do a wonderful job balancing entertainment and information.” All right. Thank you. We are writing in from the land of bourbon.
Was that Kentucky?
Al: That’s Kentucky, yeah.
Andi: Where- 95% of the world’s bourbon comes from Kentucky.
Joe: I don’t- 95%.
Al: Yep. How about that?
Joe: Oh. “Where there are more barrels aging to perfection in rickhouses than residents.”
Al: Ooh.
Joe: “We are wondering if we could spitball the sale of Beth’s business in potential retirement or reduction to part-time.
We are also hoping that possible sale yielding her $1.8 million pre-tax will be enough for her to become a stay-at-home mom with our two children. She has worked 45 to 60 hours per week for the last several years, and we are ready for a new direction.” Beth is 33, drinks little French 75s.
Al: Yep, keeps coming up, doesn’t it?
Joe: That French 75. Still haven’t tried one.
Al: Me neither.
Joe: Okay. How about you, Andi?
Andi: No. I don’t drink.
Joe: You sipping some of that?
Andi: I don’t drink anymore.
Joe: Back, down with that?
Al: Oh, okay.
Joe: let’s-
Al: I had a lot of spritz, Aperol Spritz in Italy.
Joe: Super fancy. Super fancy.
Andi: And just as a reminder, the French 75 is gin, champagne, lemon juice, and sugar.
Joe: Gin- Damn … champagne, lemon juice- I know … and a little bit of sugar. Damn. All right, French 75. Okay. And he, let’s see, Beth drives a ’76 or 26 Lexus TX500.
All right. “I’m 35, prefer a locally distilled Woodford Double Oak bourbon, neat,” okay, “and drive a ’25 Tundra.” I don’t know. I, don’t, I can’t drink bourbon neat. I need a little bit of ice
Al: Need a little ice, yeah.
Joe: I do.
Andi: So if it’s a choice between neat bourbon or bourbon with a giant ice cube or c- bourbon with regular ice, you’re gonna drink all three of them.
Joe: I will drink all three of them.
Al: If it’s presented.
Joe: Of course. If it’s presented, I will-
Al: With reverence.
Joe: I would say, “Hey, can you throw a couple cubes in here?”
Al: Yeah. And, not one big giant one.
Joe: If- Not, yeah. But it w- I’ll drink whatever. You’ll st- you’ll still drink it. If there’s no cubes, I will take a big one. If you don’t got a big one, I’ll just do it neat.
Al: You know what I don’t like about the big ice cube?
Joe: What?
Al: Is you take a drink and then the ice cube goes down- Which is- … it splashes
Joe: Yeah. I- Don’t you have, like, a big ice cube maker?
Al: No, I don’t.
Joe: Oh,
Al: no. No. Okay, good. No, not, me.
Joe: Good for you.
Al: You know I’m a beer guy.
Joe: Good for you.
Al: I don’t deal with that stuff.
Joe: No big cubes. But you have, like, 15 mugs in the freezer though, right?
Al: Yeah, ’cause I’m a beer guy.
Joe: Which is always-
At least
Okay. All right. Including child c- all right, where are we at here?
Al: In fact, we don’t have any food in the freezer. It’s just beer and my cups.
Joe: Just beer mugs.
Al: I like them cold. O-
Joe: okay. all right. So we’re back to Beth and Rip here. Okay. Including child care of $2,200 a month, our living expenses are $15,000 a month, m- mainly our mortgage, student loan payments, and Beth’s car payment. Ideally, we’ll have enough for her to either stop working or work part-time making $30,000 to $50,000 a year. We would take the income and fully invest it, hopefully yielding around 8% in the overall markets.
We currently make $300,000 and I think I would like to retire to 100% of the post-tax income. We love to travel and will definitely increase time abroad after retirement. I have a pension with a COLA only until retirement at 50… I have a pension with a COLA only until retirement,” okay? “At 57 I’ll be eligible-
Al: Okay
Joe: and with full double life it pays $60,000 in today’s dollars. We have $145,000 in traditional 401(k)s, $15,000 in Roth 401(k), $19,000 in an HSA that’s invested, $12,000 in my company stock, and $15,000 in an old 401(k) of Beth’s. All of our investing has been into the business and into my retirement accounts for the last several years.
Currently I’m putting 3% of my 170,000K into the traditional, 5% into the Roth with a 3% match. $2000 a year goes into the HSA and $10,000 per year into company stock which is at a 10% discount.”
Al: Okay.
Joe: “We have increased our investing percent by 1% each year and intend to keep doing that with a long-term goal of 25% as long as we both work, but I don’t think it’s possible when sh- when she stops.”
Al: Okay.
Joe: I like that move.
Al: Yeah, I like it too.
Joe: 1% a year?
Al: I’ve heard that on this show.
Joe: I have. I’ve heard that too- … from very smart people. “If Beth stops working now but we invest the payouts for the business, it will take three years to receive. Will it be enough for her to completely stop, or will she have to go to work part-time?
She has said she actually thinks she would like to be doing around 40, so if she didn’t sell and waited, but her number were to only go up 5% a year, would it leave us in a worse position due to missing out on seven years of compound interest?” Not sure if I follow
Al: that. Yeah, it took-
Andi: I read that a few times. She said she’d be d- she would like to be done around 40, not doing around 40.
Al: Yeah. What, he’s- So she wants to be retired … suggesting is what if the company only goes up 5% per year, and if we’d sold now, we’d have all this money that we could invest.
Joe: At 7%.
Al: I think, well, over seven years. He didn’t really say what the growth rate would be.
Joe: Well, he said s- 8% or seven. What? yeah.
Al: Somewhere, huh?
Joe: Yep, somewhere.
Al: Yeah, well hopefully yielding 8% in the market. Yeah. You’re right. Mm-hmm. You’re right about that. So yeah, I guess that would be true. If, the company only goes up 5% a year and you’re foregoing 8%, maybe so. But that’s what that… And then, but then he goes on.
Joe: “We would still receive her income by waiting and also investing more each year. Beth actually expects t- 10% growth, so waiting would potentially often, or offer even a bigger boost.” Would we even need it? Thank you for your spitball.” Man, that was a tough email.
Al: It’s,
Joe: it- I’m not gonna lie …
Al: it’s a little
Joe: tough
Rip-
Al: Yeah …
Joe: must have been drinking a little bourbon-
Al: You think?
Joe: … when he typed this one out.
Al: All right. Well, let me maybe translate what I think I heard.
Joe: Okay. So- Well, she’s got a business.
Al: Yeah
Joe: She wants to sell it.
Al: She thinks she’s gonna get 1.8 million pre-tax.
Joe: Okay.
Al: And b- selling a business, assume little or no basis, assume capital gains.
it’s probably, I just used… Well, I don’t know what the state of- Kentucky … Kentucky is, but so in Calif- well, in the federal would be 20%.
Joe: Mm-hmm.
Al: Probably would not be the 3.8%, net investment income tax ’cause it’s not a passive business. So let’s go 20%.
Joe: But they net 1.3.
Al: Yeah. Yeah, 1.3, you know, and add that to what they have, of- 200,000
a couple hundred. Yeah, maybe, adding up 1- 1.5, 1.6, 1.7, something like that. Now, if he makes 170 and she’s making 30 to 50, that can cover their 180,000 without touching, you know, those- The payments
Joe: … payments. Mm-hmm.
Al: And so that works. But then when the payments stop, can she stop working? like in other words, l- let’s say at that point with growth, maybe they have 1.8 million and they, need…
Well, let’s see. He’s making 1-
Joe: What payments are you referring to?
Al: She’s gonna get three payments of four- of roughly 600,000 each.
Joe: For the, for the business.
Al: For the business.
Joe: Got it.
Al: So we’re s- we’re suggesting that after tax, that might a- add up to 1.3, 1.4 million. Add that to the 200 they already have, maybe it’s 1.6, plus growth.
Joe: Yep.
Al: Probably not 2 million, but 2 million’s an easy number just to keep in our head, so close to 2 million, let- let’s just say is what they got.
Joe: Yep.
Al: Two, he’s making 170, they’re spending 180. Could the 2 million produce the enough income for the shortfall? The answer is probably so, right?
Joe: Mm-hmm.
Al: Yep. I mean, let- let’s say with taxes, they need 40-
Joe: Well, they’re gonna save…
Well, if, she’s at home- Yeah … do they still need childcare of $2,200 a month?
Al: Well, I think they do if she’s working part-time.
Joe: Yeah, probably right.
Al: Yeah. Maybe they could stop it after that, maybe.
Joe: Well-
Al: Potentially …
Joe: yeah. it’s close.
Al: It’s close.
Joe: But retiring at 35 and 33- Well, I don’t think- … she’s, gonna stop working.
she’s got- She built a business.
Al: Yeah.
Joe: I don’t think, like, business owners can stop working at 33. Well- She’s gonna find another business to start.
Al: She, will, but probably not right away, ’cause she wants to be with her two kids, and I understand that I mean, they’re young kids probably. I mean, she’s only 33.
Joe: Yeah.
Al: But yeah, I would say eventually, yeah, she’d probably wanna go back. The kids go, to kindergarten, and she’s got a little more time, so she’ll probably start something out of the home.
Joe: There’s so many moving parts in here.
Al: Yeah, there are.
Joe: I mean, this is a, a… And, like, back of the envelope spitball, it’s like, “Yeah, sure, it looks all right.”
But there’s probably 10 different strategies that they have to probably dive in a little bit more. You’re selling a business. I know. You’re gonna stop working. You have, kids that are young that, do you wanna plan for college? You have- Mm-hmm … you know, y- are you, how much can you save and still be all right?
Y- you know, so there’s, like, a lot of- Mm-hmm … different things that you probably wanna dial in a little bit more, especially if your wife is selling a business for $1.8 million.
Al: Right. and in this particular case, it looks like they’re thinking installment sale, which means three payments and, every time you, have an installment sale, there’s a risk- Risk
that you’re not gonna actually receive that payment, and you may have to take the business back, and maybe then it could be kinda run into the ground. So you just have to know what those risks are when you do this, and there’s lots of ways to sell. You could sell cash. It depends who you sell to. You could get some equity in the other company.
Maybe help them out as a consultant. Still make a little. Maybe that’s how they make the, she makes the 30- The $30 million … 30 to 50, and maybe that could continue, and still she gets to be at home with the kids. So you’re right. There, there’s a lot to this potentially. Got it. But, it se- it seems like when you’re spending 170, and I mean, you’re spending 180, and husband makes 170, and you’re gonna end up with a million and a half to two million. Well- Seems like that’s, that works
Joe: … pencil’s out just fine.
Al: Yep. Yep.
Joe: All right. Congratulations, Rip and Beth. let’s move on.
Al: Okay.
Andi: Notice that Joe ran the numbers, said it pencils out fine, but then said there are probably ten different strategies underneath it he’d want to dig into. When to take the business payments. What the tax hit looks like. Whether she goes back to work at all. College for two kids who aren’t even in school yet. At that point you’re well past a spitball and into needing a real plan for the future. When you schedule a free financial assessment with the experienced professionals at Pure Financial Advisors, they’ll take a comprehensive look at your entire financial picture: your assets, your taxes, how you’re invested, your income, and your goals. They’ll analyze where your gaps are and help you develop a plan that fits your retirement needs. The financial assessment is free, there are no strings attached, and you can do it in person at one of our offices in Seattle, Chicago, Denver, Phoenix, Salt Lake City, Nashville, Northern and Southern California, or online from anywhere in the country. We’re in the end-of- year tax planning season so the calendar is filling up fast. Click or tap the link in the episode description to get your meeting on the books ASAP.
Two Teachers, $1M Saved, and a Gap Year at 34. Is That Crazy? (Leeroy & Belle, IA)
Joe: Let’s go to, hello, Joe, Big Al, and most importantly, Andi.
Al: Yeah. Most importantly.
Andi: Thank you.
Joe: Good part. Yeah. Leeroy and Belle here.
Andi: They, I’ll stop there. I cannot find a reference for that.
I think those are just their names.
Al: Oh, okay.
Joe: Leeroy
Al: I was just thinking when sh- when, when he or she said, “Most importantly, Andi.” Can you imagine this show without Andi?
Joe: Absolutely not.
Andi: You guys had a show without Andi before.
Al: I know. It wasn’t very good.
Joe: Oh, wow. Third person.
Al: Right? That’s, you love that, huh?
Joe: Oh. I love third person. Joe loves third person.
Al: You know, remember when it was just Alan and Joe?
Joe: Oh, man. L- all right. Let’s go back to Leeroy.
Al: Leeroy and Belle.
Joe: Now, have I ever seen Leeroy spelled L-E-E-R-O-Y?
Al: Well-
Joe: Is that how you spell Leeroy?
Al: Well, Andi, I, I actually did a little research on this, and it’s Once Upon a Time, a TV series, and Leeroy is patterned after Grumpy, and Belle is, Belle, Beauty and the Beast.
Joe: What are you talking about?
Al: That was a, it was a TV show with those characters
Joe: Oh, okay.
Al: That’s what I’m talking about.
Joe: Got it.
Al: Are you paying attention?
Joe: Not really. “I’ve been a big fan of the show for the last couple of years listening on my commute. I’m 34 and Belle is 33. We have…” But you said Leeroy’s grumpy?
Al: Yeah, he’s patterned after the character Grumpy of, like, Snow White and the Seven Dwarfs.
Joe: Oh. Okay. Oh, okay.
Al: that’s what ChatGPT said.
Joe: Got it. Chat, your boy.
Al: My boy.
Joe: Okay.
Al: Yeah.
Joe: “I’m 34, Belle’s 33. We are married and live in Iowa.”
Al: Okay. ”
Joe: We both are teachers and want to do an unconventional gap year next year. In our 30s.”
Al: Mm-hmm.
Joe: “We have no kids and want to move to Wisconsin.” Little Wisconsin, huh?
Al: Okay.
Joe: I just read that Iowa was, like, one of the best places to retire.
Al: Really?
Joe: I did read that.
Al: Did they say why?
Joe: cost of living.
Al: Cost of living, yeah. Friendliness.
Joe: Friendliness. Neighbors. Yeah.
Al: Community.
Joe: Mm-hmm.
Al: Got it. Okay.
Joe: Even though the winters are quite- Health, health there … healthy. Yeah. Yeah.
Al: Yeah.
Probably.
Joe: So, but they wanna move to Wisconsin, so they’re gonna do a little gap year and travel-
Al: Yeah,
Joe: well- … in leisure now.
Al: Well, they kind of, well, well, they switch it up a bit.
Joe: Yeah. Okay. ‘Cause they’re getting old, 34 and 33. Get that gap year in.
Al: I’ve got kids older than them.
Joe: I know you do. “Instead of immediately switching to another job, which could potentially be for the rest of our working career.”
This gap year would be for the 2007-2028 school year, and we would find jobs for our 2028-2029 school year- Okay … in Wisconsin, which would be closer to family and friends.”
Al: Okay.
Joe: So they’re both teachers?
Al: Yep, both teachers.
Joe: All right. “Importantly, I, Leeroy- … drives a 2016 Prius and Belle drives a 2008 Subaru.
My drink of choice is brandy old-fashioned, hence why we want to move to Wisconsin.”
Al: Oh.
Joe: yeah. all right.
So Belle, she likes a Paloma. Our combined income is $118,000 a year and we save a lot, usually over 50%, maxing out the IRAs and close to maxing out our four 3Bs every single year. Here are the details.” Okay.
All right, this is long.
Al: That’s a lot of details. Let’s go.
Joe: All right. Roth IRA, 150.
IRAs, 403(b)s, 400,000. Brokerage account, 300,000. Cash, 60,000. Full disclosure, all this money is from us saving a ton. The only windfall we had was that I, Leeroy, cashed out of a whole life policy a few years ago that I had when I was young, which was around $40,000. No debt. We rent our apartment, more flexible.
Fixed income, we have 105,000 in our Iowa pensions combined when we leave, which we can either leave in, and then to receive small monthly payments, later in life, or we can pull out that amount to invest. Social Security when we retire, good luck. Oh, he doesn’t believe in the old Social Security.
Yeah,
Al: apparently. Well, in your 30s did you?
Joe: No. It’s not gonna be there. All right. We-
Al: Yeah. N- now that I’m, Dude … getting older-
Joe: Yeah
Al: … seems pretty likely.
Joe: I know. For you. God, it’s crazy, man. It’s like, when I would read these-
Al: Yeah …
Joe: like, “Hey, I’m 50,” and I was like, “Man, wonder when…”
Al: That’s old.
Joe: “God, you’re getting old, man. This guy’s old.” And then I was like, “Man, now I’m 50.”
Al: Yeah.
Joe: How did that happen?
Al: It just happened.
Joe: It just does. Yeah, right. It does.
Al: Right.
Joe: “Retirement age. We have been interested in the FIRE moment.”
Al: In parentheses.
Joe: All right.
Al: Financial Independence Retire Early.
Joe: Oh, God. Love it.
Al: Yep.
Joe: “But for us, it’s more flexibility to retire earlier than a traditional retirement age and do the things that w- we thought we might not be able to do on a teacher’s salary.
For example, having one spouse working full-time while the other one works full-time, or, is a full-time parent.” Yeah. “Spending in retirement, we’ll see. We spend less than $50,000 annually now, so spending $100,000 in retirement in today’s dollars would be ideal. Question, is it crazy for us to do a gap year?”
Yes. Get to work.
Al: That-
Joe: Teach our children-
Al: The answer is no
Joe: … not to do gap years.
Al: The answer is no. Do your gap year. You totally deserve it. Yeah. You know, you know what? Two teachers with their retirement plans, and they’ve already saved almost a million dollars at 33 and 34. Yeah, take the gap year.
Joe: Do not do it.
Al: Take it.
Joe: You’re not gonna get a job. They’ll be like, “What were you doing this past year?” “Oh, we did a gap year.” Fail.
Al: I would respect that-
Joe: All right
Al: … as an employer.
Joe: Okay. If you were, the, principal, you would hire them?
Al: I would, I would. All right. Yeah.
Joe: All right. “We’ve looked at healthcare through Healthcare.gov, the Affordable Care Act, and thankfully it’s not crazy expensive.”
any financial considerations to keep in mind doing a gap year in our 30s? We could pass contributions to everything except the Roth IRAs. We are planning on bumping up our cash amount from now until we leave work so that we don’t need to draw down upon our investments. At this point, we’re pretty confident.
We’re going to do the gap year, and we don’t need to decide until March of 2027 to let our employers know. Again, love the show. Thanks for what you do.
Al: So you’re gonna tell them not to do it?
Joe: I don’t care- … to be honest. I don’t.
Al: Got it. Okay.
Joe: A million dollars saved at 30-some on a teacher’s salary.
Al: It’s unbelievable.
Go for it.
Joe: Yeah. What the hell?
Al: Yeah.
Joe: They must be good teachers.
Al: they’re the best.
Joe: You think they teach finance or something?
Al: They know about finance.
Joe: What are you gonna do on a gap year? How old are their kids?
Al: They don’t have kids.
Joe: Oh.
Al: they’re doing it before kids.
Joe: Well, I thought he said s- like, stay-at-home mom.
Al: Well, for later.
Joe: Oh, later.
Al: Yeah. Okay. yeah,
Joe: yeah.
I don’t know. I, think that they’re doing things quite well. Yeah. What, do you think they’re gonna do on their gap year in Wisconsin?
Al: Oh, I think they’re gonna travel. I don’t think they’re going to Wis- they’ll end up in Wisconsin. I don’t think they-
Joe: Oshkosh.
They’re gonna go to Oshkosh, and then they’re gonna go to-
Al: they’re gonna go to Florida …
Joe: go to Madison. They’re- And then from Madison, they’re gonna go to Milwaukee.
Al: That’s right. The, they might even go crazy and go into Michigan.
Joe: Yeah, they could. All right.
Al: No, I think they’re gonna… I bet they travel the country, or maybe they-
Joe: They go abroad?
Al: I think they go abroad. Why not?
Joe: Sure.
Al: You know, Robbie is a couple years older than them. When he travels, he still stays in hostels and doesn’t spend very much. you can travel pretty inexpensively.
Joe: Did he do a gap year? Is he, gapping right now?
Al: He’s not gapping, but he’s, has no trouble traveling.
Joe: Got it.
Al: Yeah.
Joe: Huh.
Al: Yeah. No. I’d say yeah, why not?
Joe: What do you think, Andi? Y- yay on the gap year or nay?
Andi: Absolutely. Life is for living. Go. Do it now. Trust me.
Al: See? There you go. That’s right. Okay.
Joe: I think I’d be bored doing a gap year.
Al: No, you’re not supposed to project- Just for a year? You’re not supposed to project you doing a gap year.
This is someone that wants to do it.
Joe: All right. Go for it.
Andi: Joe, if you had a year to do nothing but play golf and hang out and socialize, you’re saying you wouldn’t have a good time with that?
Joe: No, I wouldn’t do it.
Al: I c- I can’t i- I can’t imagine you doing a gap year.
Joe: There’s no way.
Al: It’s beyond imagination.
Joe: No.
It’s like, I love my routine.
Al: Yeah.
Could you imagine me doing a gap year?
Joe: Yes.
Al: Yeah. Totally. I mean,
Joe: yeah.
Al: You’d s-
Joe: you know, you’d be bored to tears. Aren’t you kind of in it now? I think you’re doing it now.
Al: I think if you add up my vacations every year, almost is a gap
Joe: year. Y- yeah, almost. no, I don’t… I, would not enjoy a gap year.
Al: No, I can imagine that.
In fact, if you came to me tomorrow and said, “You know what, Al?”
Joe: I’m gonna take a sabbatical.
Al: “I’m gonna do a gap year. I’m gonna say-”
Andi: Tell him to go to the doctor.
Al: “I gotta, call up Rose. Did he fall over and bump his head?”
Joe: Yeah, right. I would call a doctor. nope. No. Okay. I d- I’m not wired that way.
Okay. Because, I don’t know, then I would be, like, having cocktails every day, and then I’d just probably get fat and lazy and tired. I like getting up early, getting my workout in- Yeah … get stuff, check the boxes.
Al: Yeah. And you got a reason to get up every day and- Yes
Joe: … yeah. I like being busy. You got responsibilities.
Yeah. Sometimes it drives me nuts and-
Al: Yeah, of course, but it’s your routine.
Joe: Yeah.
Al: Yeah. I get it.
Joe: Get to see you guys.
Al: Yeah, true.
Joe: I’d miss you.
Al: Yep.
Joe: I would not miss Aaron, though.
Andi: Oh, wow.
Coast FIRE at 52: Can I Stop Saving Now and Retire at 58? (Jake, MI)
Joe: All right. Let’s, we got one more to go here.
Al: Okay. Let’s do it.
Joe: I got, “Hi, Big Al, Joe, and Andi. I asked this spitball question back in 2024, and you guys answered it on the podcast, but it took you a year and a half.”
Oh. “You guys are awesome. Joe…” Let’s, see. “Joe ripped on me for driving a cool-ass Ice 2021 metallic autumn green Subaru Outback and my love for pina coladas. How hard was that?”
Andi: He probably thinks that you lived in Seattle.
Joe: Guaranteed. Metallic autumn green Subaru? Yep. You know what movie just comes to mind with that?
It’s like-
Andi: Portlandia?
Joe: What’s that?
Andi: Never mind.
Joe: What’d you say?
Andi: I said Portlandia-
Joe: Oh, Portlandia
Andi: … which isn’t a movie.
Joe: Yeah. Something like in Portland?
Andi: Yeah.
Al: you could picture that.
Joe: Yeah, little pina coladas. Right. I don’t mind a pina colada.
Al: But he lives in rural Michigan.
Joe: I know.
Al: See, that didn’t compute to you.
Joe: I know. No, it d- Who drinks pina coladas in rural Michigan? How the hell do you even make one?
Al: That’s why you drive-
Andi: Somebody who’s dreaming of the s- tropics instead.
Joe: “I did buy an older manly GMC Canyon,” what? Duramax. Duramax. Diesel. Diesel truck, all right.
Andi: That sounds like it should be a condom.
Al: That’s a-
Joe: Duramax.
Oh. Let’s s- in 2024 and had it for a year, but sold it just because it wasn’t me.
Al: It wasn’t me.
Joe: The Duramax guy drinks pina coladas. Yeah. You, dude, I’d be drinking pina coladas while I’m driving my Duramax.
Al: that would make him cool.
Joe: Well, yeah, he lives in rural Michigan. He c- probably can drive up and down his driveway.
Al: He can
take all he wanted. Drink whatever you wanted. Rural, no one’s gonna see you.
Joe: let’s see. It just didn’t feel right for Jake. He had to get back to his Subaru.
Al: Yeah, right, right.
Joe: “In 2024, you recommended that I consider switching my Solo 401(k) to a Roth option from my traditional plan that I had. In 2025, I made that change and maxed it out last year and plan to do so this year.
Just a refresher about me, I’m in my early 50s, divorced guy that has been living way below my means for the last seven years after the divorce, maxing out my Solo 401(k), HSA, and Roth IRA every single year, saving about 50% to 60% of my income in hopes of retiring sooner rather than later. I’m a clinical social worker, and I have a…”
Oh, boy.
Andi: Infinitesimal.
Joe: In-
Andi: Infinitesimal.
Joe: Infinitesimal.
Al: That’s a, that’s a-
Andi: There you go. Well done.
Joe: What is it, like infinite?
Andi: Tiny.
Al: That’s a tiny-
Joe: Infinitesimal.
Al: That’s a, tiny wallet. Little b- Just, say it’s a tiny wallet …
Joe: little baby wallet. compared to most of your… Okay. Opulent. He’s pulling this s**t on purpose.
Al: He is. Opulent.
Joe: Thank you. “In 2024, I had around $650,000 saved, but with the strong markets and maxing out my accounts, my retirement savings are now over $1.1 million.”
Al: I think that’s excellent.
Joe: Here’s the breakdown. Okay. Roth IRA, $200,000. Roth, $140… I’m sorry, brokerage account, $200,000. Roth, $140,000.
HSA, $50,000. Traditional IRA, $750,000. I have a Coast FIRE spitball question for you.
Al: Okay.
Joe: “I’m planning to max out my retirement accounts one more year and then switch to Coast FIRE for four or five years, working part-time to cover my living expenses. Not too-”
Andi: Coast FIRE is the point where your current invested savings will compound to your full retirement target by traditional retirement age without you ever having to add another dollar
Al: Okay.
Joe: Thank you for the clarification So he, can just coast right in
Al: Coast in. Yep.
Joe: So he’s got the dollar figure, but he still can’t retire on that amount, so he’s, the assumption rate of return that he’s using, he can coast right in. But coast right in- What if he doesn’t hit the return? That’s not a coast.
Now he’s gotta pedal.
Al: He’s gotta pedal.
Joe: He’s got-
Al: Yeah.
Joe: It’s not looking like it that is. Gotta get that two through and just-
Al: Yeah.
Joe: … jumpstart that bad boy.
Al: Right. Yeah.
Joe: “I finally will pull the plug, on part-time, hopefully when I’m around 58 or 59 years old. I’m planning to work, just two long days per week and take 10 full weeks of vacation each year in addition to having four or five days off each week to do more traveling now in my 50s versus waiting until in my 60s and fully retired.”
Al: Damn.
Andi: Does this feel like a little bit of a theme to you?
Joe: Yeah. Sure does.
Al: Mm-hmm.
Joe: “My spitball is-
Andi: As he rolls his eyes.
Joe: “Should I just not invest anything into my retirement accounts during those four or five years of working part-time and just fund my life through work? Or should I take some withdrawals from my brokerage account to fund my expenses, instead contribute some of my earned income to my Solo 401(k), Roth IRA, HSA?
If so, which accounts make the most sense to fund during those four to five years? I plan to work enough to generate $70,000 worth of income per year, which is my projected living expenses in those four to five years. Any thoughts?” just live off your c- income. Don’t touch your investments. Let ’em continue to grow.
Right. That’s my two cents.
Al: Yeah, but he’s thinking… Yeah, so y- would you r- would you rather have him put money into a Roth from his salary and then draw from the brokerage account?
Joe: Yeah, I probably, maybe that
Al: I think that’s what he’s asking.
Joe: But he said Solo 401(k), Roth IRA- Well- … he did say?
Al: Yeah. Well, yeah, Solo 401(k) with a Roth option, I think.
Joe: Yeah, if he’s gonna go- Yeah … all Roth, then yeah. Yeah. Fund your Roths.
Al: Yeah,
Joe: But you’re funding your Roths with your brokerage account. Right. You’re not living off your brokerage account. That’s right. You’re still living off- It’s,
Al: it’s like a-
Joe: … because you’re self-employed …
Al: it’s like a big contribution.
It’s like-
Joe: Yeah, you just take the money from your brokerage account, put it into the Roth account, so it’s the same Yeah. You, the, use the same investment if you want.
Al: Yeah.
Joe: So it’s just moving it from one pocket to the other pocket. yeah,
yeah. But don’t take those dollars out and, spend them and spend.
Al: Right.
Joe: Right. just move those and fund your retirement accounts with those dollars, and then just spend, the, y- your paycheck as it comes in.
Al: Right. Now, I, he didn’t really ask for it, but I, thought I’d do a little math here.
Joe: Okay.
Al: It’s a little complicated. So I’d ran, Well, first of all, he’s got a million, 1.1 million, now.
S- I did a 6% return for one year, adding about 30 grand. I don’t know what the match is, but he gets to about 1.2 million. And then I said, “Okay, so now we coast.” We coast for four more years, 6%, no contributions, so he ends up with about a million and a half.
Joe: Okay.
Al: Then it’s like, okay, so w- he wants to spend 70, so now we’re talking about a five-year period, 3% inflation rate, so that’s about 81 grand.
81 grand and a million and a half is about 5.4% distribution rate. At 58, 59 might be a little tight.
Joe: He needs to pull that from the portfolio- Mm-hmm … at that point?
Al: Yeah.
Joe: Okay.
Al: Now, of course, he didn’t m- mention what his Social Security was, so maybe this helps save him, but just based upon what I quickly ran, I’m not s- this seems pretty tight to me.
If, it were me and I want, and I really wanted to do this plan, and I really could work two days a week, and make w- you know, the 70 grand-
Joe: 75 grand, yeah …
Al: and still get 10 weeks of vacation, I would do that till I was 65.
Joe: Right.
Al: Why not? And then-
Joe: Or 70, even …
Al: yeah. W- when, I’d do it until I collected Social Security, and certainly 65 for, to, get Medicare.
Joe: Right.
Al: That’s what I would do.
Joe: Yeah. That- You got a couple of things to do during the week to keep you busy, but you’re j- Yeah … it’s more, way more time off than work.
Al: Yeah, I, that’s what I would do, personally. And I think, w- if, he gets to f- 58, maybe he’ll sort of realize this is actually a pretty good deal, working two days a week- Yeah
and all this vacation.
Joe: Yep.
Al: I have a friend that’s doing something similar, actually is a nurse, and he’s in his 70s and he works couple da- he actually works a couple days a month, and keeps some salary coming in for travel, and it- Sure … works out pretty well.
Joe: Yeah. Very cool.
Al: Yeah.
Joe: All right. Cool. I gotta run.
Al: Okay.
Joe: That’s it. I, Yeah, Andi. Well, thank you for putting that nice collage of, early retirement together. Yeah. That looked quite joyful. It’s
Al: fun. Yes.
Joe: All right. Keep your questions coming. We’ll get them answered at some point. Show’s called Your Money, Your Wealth®. We’ll see you next time.
Al: Cool.
Joe: Thank you very much.
Outro: Next Week on the YMYW Podcast
Andi: Dutton Ranch, and the brandy old-fashioned in the Derails at the end of the episode, so stick around.
Coming up next week on YMYW: Should David Larry take on a $1.2 million mortgage to build the house he wants? Leon threw a half a million dollars at a 2.75% mortgage and wonders if the fellas would consider a mortgage recast. What are the pros and cons of a staggered retirement, 4 years apart, for Louden and Carla? And should Brian and Judith stop saving to their 401(k) and pay down debt instead? Make sure you’re subscribed or following us wherever you watch or listen so you don’t miss it. And if you haven’t signed up for the YMYW newsletter yet, you’ll find the link in the episode description.
Pure Financial Advisors is a registered investment advisor. This show does not intend to provide personalized investment advice through this podcast and does not represent that the securities or services discussed are suitable for any investor. As rules and regulations change, podcast content may become outdated. Investors are advised not to rely on any information contained in the podcast in the process of making a full and informed investment decision
The Derails: Giant Ice Cube, Dutton Ranch, Wisconsin’s Brandy Old-Fashioned
Al: Do you like, you like bourbon with a big ice cube?
Joe: No, I’m not a big ice cube guy. I like-
Al: Yeah … I like the cube.
Oh, that’s what you told me. you, yeah, you like smaller.
Joe: Yes. I don’t like, like when I get-
Al: Yeah …
Joe: let’s say bourbon on the rocks- if it’s a big rock I gotta like swirl it around to get the thing cold. I like ice cubes in there to cool it right away- But you wouldn’t- … and then I-
Al: You wouldn’t send it back.
You would still drink it.
Joe: For sure I would still drink it. I don’t think, I don’t send anything back.
Al: It’s not, it’s, I, it’s not that important.
Joe: Right. No. I don’t think I’ve sent anything back. Okay. I dated a girl that would send-
Al: Yeah …
Joe: and we didn’t date very long.
Al: I don’t think I’ve ever sent anything back either.
Joe: It’s like, man, it’s, they could give me a chicken that’s raw and if I ate it I’d get salmonella, I’d still-
Andi: So you don’t even send food back?
Joe: I would not send anything back. Oh. Wow. I’d be like, “This was wonderful,” and I’d just put a napkin over it- I think- … and I’d just go to-
Al: I think one time I sent something back that wasn’t cooked enough, but they
just- re-cook it
Joe: … yeah, just- Yeah … put it in the oven a little bit more.
Al: Yeah.
Joe: Come on. Yeah. No.
Al: Yeah.
Joe: I’m not a sender-backer.
Al: Okay.
Joe: I’ll grin and bear it. Yeah. Th- I might not ever go back there.
Al: And, you’re probably like when you buy something, which is seldom, you would never go back and return it.
Joe: Ever.
I’ve never returned a thing in my life.
Andi: That’s from Yellowstone.
Joe: Did you see the new series?
Al: I haven’t seen the new series. Have you?
Joe: The Dol-
Al: The Yellowstone?
Joe: Well, no, it’s not, it’s- Oh, it- … it’s, with Rip and Beth …
Al: oh. Oh, that’s right.
Joe: It’s Du- it’s, Dutton Ranch it’s called.
Du-
Al: That’s right, Dutton Ranch. No, I haven’t seen it.
Joe: No?
Al: You not, I’m not huge-
Joe: No
Al: … fan of that.
Joe: You don’t? You didn’t like, Yellowstone? You don’t like-
Al: Not really.
Joe: Taylor Sheridan?
Al: Too p- no, too much conflict. I want happier stuff.
Joe: Well, you know, Christmas is coming. Hallmark movies.
Al: Ah, Hallmark, yeah.
Joe: So, like, you didn’t watch Landman?
Al: No.
Joe: No? Don’t like that either, huh?
Al: No.
Joe: Did you ever watch the movie Sica- Sicario?
Al: You already know the answers to all these- … so just keep rattling ’em off and just assume the answer’s no.
Joe: Okay. All right. Here we go. Rip and Beth.
Joe: A lot of brandy in Wisconsin?
Andi: Yeah, I’m, I-
Al: Well, folk-
Andi: … didn’t get the reference there
Al: Maybe a lot of old fashions maybe?
Joe: Nah.
Al: No?
Joe: I, don’t think I’ve ever drank a brandy old fashion.
Al: Yeah. They’re all about whiskey, right?
Joe: Yeah, I don’t really care for brandy. Do you like brandy?
Al: I don’t like any of that stuff.
Joe: Oh.
Al: I don’t like whiskey or brandy- Well- … or scotch …
Joe: okay. Yeah, brandy. My aunt drank brandy.
Yeah.
I’m trying to-
Andi: Wow, the Wisconsin brandy old fashion is the state’s unofficial official cocktail. Oh, Famous for swapping in traditional bra- whiskey for brandy, typically Korbel, and topping with, topping the drink with soda.
Joe: So- All right …
Al: maybe you don’t know your neighbor that well.
Joe: Well, my aunt drank a lot of brandy.
Al: Okay.
Joe: brandy cloudy. It was like-
Al: Cloudy? Okay.
Joe: Yeah. You know what cloudy is?
Al: No.
Joe: That little water with a little squirt of soda water, I think.
Al: Oh, okay.
Joe: I think that’s cloudy.
Al: Right. Okay.
_______
Listen to the YMYW podcast:

Amazon Music

AntennaPod

Anytime Player

Apple Podcasts

Audible

Castbox

Castro

Curiocaster

Fountain

Goodpods

iHeartRadio

iVoox

Luminary

Overcast

Player FM

Pocket Casts

Podbean

Podcast Addict

Podcast Index

Podcast Guru

Podcast Republic

Podchaser

Podfriend

PodHero

podStation

Podverse

Podvine

Radio Public

Rephonic

Sonnet

Spotify

Subscribe on Android

Subscribe by Email

RSS feed
YouTube Music
IMPORTANT DISCLOSURES:
Pure Financial Advisors is a registered investment advisor. This show does not intend to provide personalized investment advice through this podcast and does not represent that the securities or services discussed are suitable for any investor. As rules and regulations change, podcast content may become outdated. Investors are advised not to rely on any information contained in the podcast in the process of making a full and informed investment decision.
• Investment Advisory and Financial Planning Services are offered through Pure Financial Advisors, LLC, a Registered Investment Advisor.
• Pure Financial Advisors LLC does not offer tax or legal advice. Consult with your tax advisor or attorney regarding specific situations.
• Opinions expressed are not intended as investment advice or to predict future performance.
• Past performance does not guarantee future results.
• Investing involves risk including the potential loss of principal. No investment strategy can guarantee a profit or protect against loss in periods of declining values.
• All information is believed to be from reliable sources; however, we make no representation as to its completeness or accuracy. As rules and regulations change, content may become outdated.
• Intended for educational purposes only and are not intended as individualized advice or a guarantee that you will achieve a desired result. Before implementing any strategies discussed you should consult your tax and financial advisors.
CFP® – The CERTIFIED FINANCIAL PLANNER® certification is by the CFP Board of Standards, Inc. To attain the right to use the CFP® mark, an individual must satisfactorily fulfill education, experience and ethics requirements as well as pass a comprehensive exam. 30 hours of continuing education is required every 2 years to maintain the certification.
AIF® – Accredited Investment Fiduciary designation is administered by the Center for Fiduciary Studies fi360. To receive the AIF Designation, an individual must meet prerequisite criteria, complete a training program, and pass a comprehensive examination. Six hours of continuing education is required annually to maintain the designation.
CPA – Certified Public Accountant is a license set by the American Institute of Certified Public Accountants and administered by the National Association of State Boards of Accountancy. Eligibility to sit for the Uniform CPA Exam is determined by individual State Boards of Accountancy. Typically, the requirement is a U.S. bachelor’s degree which includes a minimum number of qualifying credit hours in accounting and business administration with an additional one-year study. All CPA candidates must pass the Uniform CPA Exam to qualify for a CPA certificate and license (i.e., permit to practice) to practice public accounting. CPAs are required to take continuing education courses to renew their license, and most states require CPAs to complete an ethics course during every renewal period. Pure Financial CPAs do not act as your accountant or provide tax services unless specifically stated.